The MSME credit gap in Southeast Asia: why 70% of small firms cannot borrow
A garment factory wins a large order. The buyer pays in 90 days. The factory needs fabric today. The bank says no, and the moneylender says yes at 36% a year.
Most small firms in Southeast and South Asia cannot get a formal loan. The data to lend to them already exists.
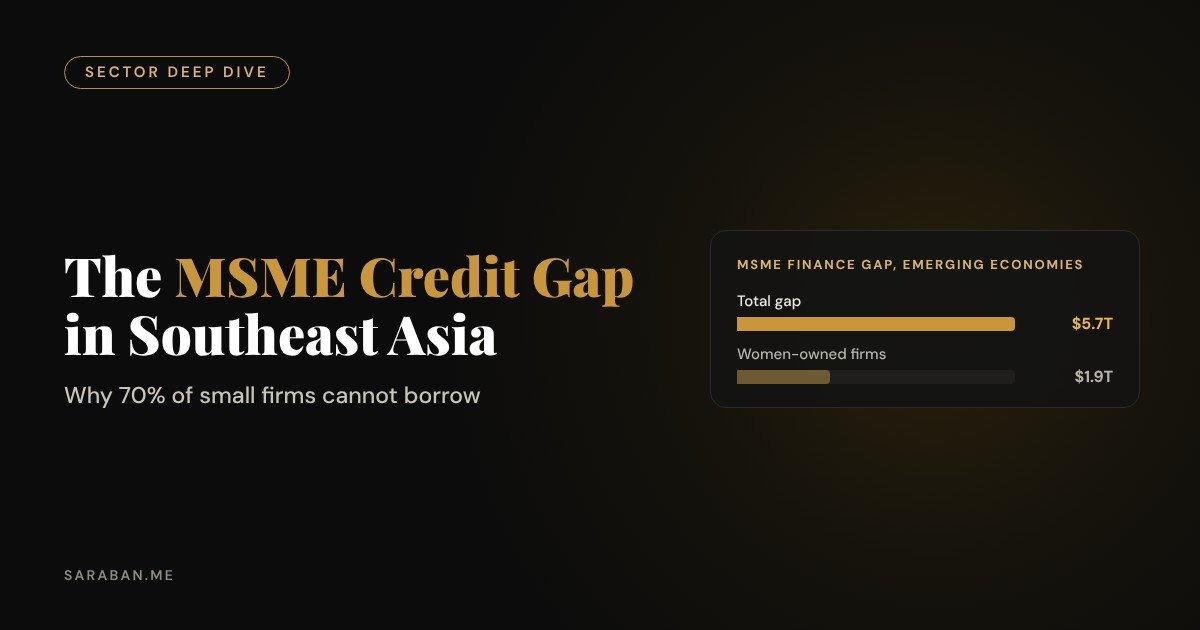
The msme credit gap is the difference between the credit small businesses need and what formal lenders provide. Globally, the SME Finance Forum and IFC put the gap for micro, small and medium enterprises in emerging economies at several trillion dollars. In South and Southeast Asia, it shapes how millions of firms grow, or fail to.
This deep dive looks at the size of the gap, why banks keep saying no, and how embedded finance is turning invoices and purchase orders into credit.
How large is the MSME credit gap?
| Indicator | Figure | Source |
|---|---|---|
| MSME finance gap, emerging economies | About $5.7 trillion (2019 estimate, up 27% from 2015) | SME Finance Forum / IFC |
| Share attributable to women-owned firms | About $1.9 trillion | SME Finance Forum / IFC |
| MSMEs as share of SEA businesses | More than 97% | Royal Park Partners, 2024 |
| MSME financing gap, Bangladesh | $2.8 billion | IFC |
| Bangladeshi MSMEs financially constrained | 39% | IFC, via Friedrich Naumann Foundation |
| Share of Bangladeshi bank loans going to SMEs | About 20% | BIBM |
Why banks say no
Traditional SME lending is built for firms with audited accounts, collateral and a credit history. Most small firms in the region have none of these, even when their underlying business is healthy.
| Bank requirement | Typical small firm reality |
|---|---|
| Audited financial statements | Cash books or none at all |
| Collateral of 100-150% of the loan | Leased premises, machinery already pledged |
| Credit bureau history | No file, or a thin one |
| Three to four weeks to approve | Needs cash within days to fulfil an order |
The result is a market where firms with genuine orders and real cash flow borrow informally at 36% or more, because the formal system cannot see what they are.
The factory cash cycle, in numbers
Take a factory with a $500,000 purchase order, paid 90 days after delivery. It must buy materials now.
Informal loan
36% a year
About $44,000 in interest on $500,000 for 90 days, often more with fees.
Invoice financing
1.5-2% for 90 days
About $7,500-10,000 on the same amount, funded within days.
The difference is not just cheaper money. A factory paid in days instead of months can bid on more orders, pay suppliers on time and hire more workers. Working capital is productivity.
Closing the MSME credit gap with embedded finance
The data needed to lend already exists inside the systems small firms use every day: purchase orders, invoices, shipping documents, mobile money flows and supplier payments. Embedded finance reads that data and offers credit at the point of need.
| Product | Data used | Where it sits |
|---|---|---|
| Invoice financing | Confirmed invoices from known buyers | Accounting or e-invoicing software |
| Purchase order finance | Orders from creditworthy buyers | Buyer procurement platforms |
| B2B buy now, pay later | Purchase history with suppliers | B2B marketplaces and distributors |
| Merchant cash advances | Card or wallet sales | Payment gateways and POS systems |
Invoice financing reaches fewer than 5% of SMEs in Southeast Asia, against 20-30% in developed markets. That gap is not technical. It is about distribution, and about lenders willing to underwrite on data rather than collateral.
What works, and what to watch
- Anchor buyers reduce risk. Lending against invoices from a known global buyer is safer than lending to the supplier alone.
- Short tenors limit losses. Most embedded SME credit runs 30-120 days.
- Fraud controls matter. Fake or duplicated invoices are the main operational risk; e-invoicing helps.
- Regulation is catching up. Bangladesh and other markets are building digital public infrastructure that makes consented data sharing easier, as LightCastle Partners has documented.
The core idea
The small business does not lack creditworthiness. It lacks a lender that can read the evidence of creditworthiness it already produces.
Where the gap is widest, and where it is closing
The msme credit gap is not uniform across the region. It is narrowing fastest where governments have built digital rails and data-sharing rules, and widest where small firms still run on cash.
| Market | Enabler in place | Main constraint |
|---|---|---|
| India | GST e-invoicing, account aggregator framework | Scale of informal micro-enterprises |
| Indonesia | Large B2B marketplaces and distributors | Fragmented island logistics |
| Philippines | Open finance framework under development | Low SME formalisation |
| Bangladesh | Wide mobile money reach, credit guarantee scheme | Limited digital invoicing and data sharing |
| Vietnam | E-invoicing mandate | Bank-led lending culture |
The pattern is consistent: once invoices and payments are digital, lenders can underwrite small firms at scale. The fintech opportunity is to get there before the incumbents do.
The MSME credit gap is not a shortage of good borrowers. It is a shortage of lenders that can see them.
Frequently asked questions
What is the MSME credit gap?
It is the difference between the financing micro, small and medium enterprises need and what formal lenders supply. IFC and the SME Finance Forum estimate it at about $5.7 trillion across emerging economies.
Why can small businesses in Bangladesh not get bank loans?
Many lack audited accounts, collateral and credit histories that banks require. IFC estimates 39% of Bangladeshi MSMEs are financially constrained.
How does invoice financing help SMEs?
A lender advances most of an unpaid invoice’s value immediately, then collects when the buyer pays. The SME gets working capital in days instead of waiting 60-90 days for payment.
Which SME product gets built first at scale: invoice financing, B2B buy now pay later, or working capital for exporters?
Share your view in the comments. This post is part of a 50-part series on fintech in South and Southeast Asia; see the full series index.
Keep reading
- The trade finance gap in Asia: a $2.5 trillion problem hiding in plain sight
- The supply chain finance playbook: what China built, and what SEA can copy
- The Bangladesh fintech market: a 2026 deep dive
Sources
- SME Finance Forum and IFC, MSME Finance Gap
- The Financial Express, “MSMEs in Bangladesh face $2.8b financing gap: IFC”
- Friedrich Naumann Foundation, “A brief overview of SMEs in Bangladesh”
- LightCastle Partners, “MSME financing in Bangladesh: unlocking a digital pathway to credit access”
- Fintech News Singapore, “Fintech Southeast Asia: the driving force behind its golden age” (Royal Park Partners data)
This article is for information and education only. It is not investment, legal or tax advice, and it is not an offer to sell, or a solicitation of an offer to buy, any security or interest in any fund. Market figures come from the third-party sources listed and may change; please check the original sources.