Agri supply chain finance: closing the farmer cash gap in South Asia
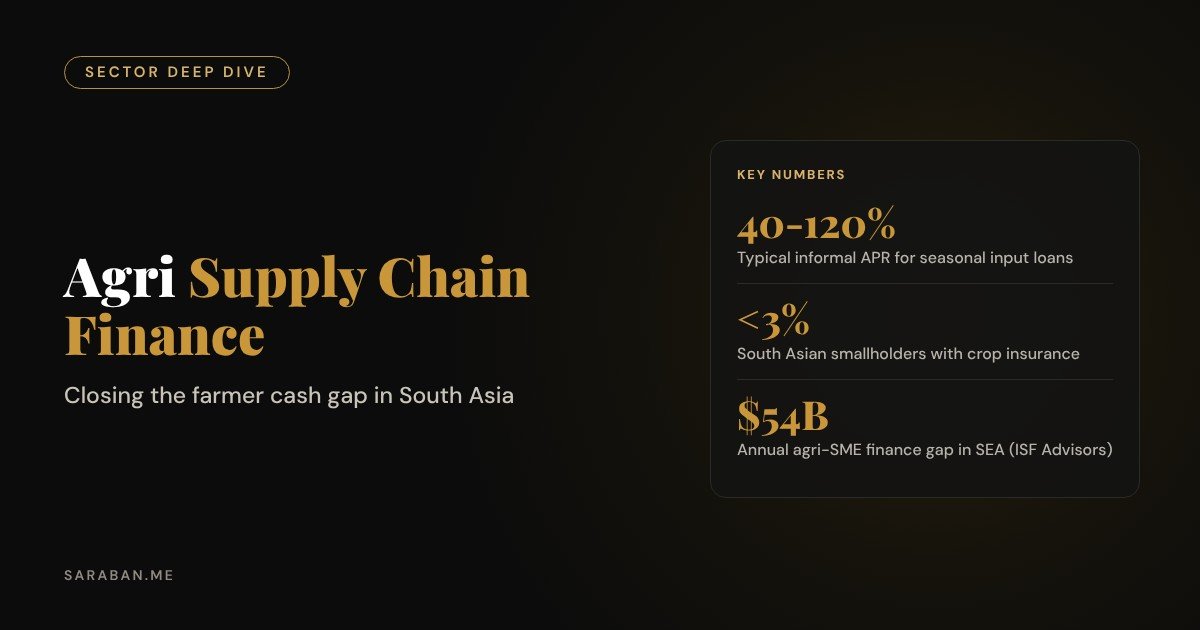
Millions of South Asian farmers are paid in cash and borrow at 40% to 120% a year from moneylenders. The bank charges nothing, because the bank says no.
The supply chain that feeds half the planet has almost no financial infrastructure inside it. That is the opportunity.
Agri supply chain finance means using the transactions inside a farm-to-market chain, such as purchase orders, deliveries and payments, to lend money to the people in it. It replaces land titles and payslips, which most smallholders do not have, with data they already create every season.
This deep dive maps where cash gets stuck in the crop chain, why banks stay out, and which fintech models are turning supply chain data into credit.
Where the cash gets stuck
A rice or vegetable farmer spends money months before earning any. Seeds, fertiliser and labour are paid in the planting season; income arrives after harvest, and often weeks after delivery to a trader or processor.
| Stage | Money flow | Typical financing today |
|---|---|---|
| Planting | Cash out: seed, fertiliser, labour | Moneylender or input dealer credit at high rates |
| Growing | Cash out: irrigation, pesticides | Family savings, informal loans |
| Harvest | No income yet | Sale to first buyer at a discount for quick cash |
| Delivery and payment | Income arrives, often delayed | None; payment terms set by the buyer |
Each gap is filled by someone charging for it. The trader who pays cash at the farm gate takes a discount. The input dealer who extends credit builds it into the price. The moneylender charges explicit interest that can exceed 100% a year.
Why banks do not lend to farmers
- No collateral. Many smallholders farm leased or informally held land with no clear title.
- No documented income. Sales are in cash, with no records a credit officer can read.
- High cost to serve. Small loans in rural areas cost as much to process as large urban ones.
- Correlated risk. One bad monsoon can hit an entire district’s borrowers at once.
Each reason is real. But each one assumes the lender knows nothing about the farmer. Inside the supply chain, someone usually knows a lot.
How agri supply chain finance works
The platform, processor or aggregator buying the crop already holds the data a lender needs: how much each farmer delivered last season, at what quality, and how reliably. That record turns into a credit file.
| Product | Who it serves | What it replaces | Data used |
|---|---|---|---|
| Input financing | Farmers at planting | Moneylender loans | Past deliveries to the buyer |
| Receivables finance | Farmers and aggregators after delivery | Discounted farm-gate sales | Confirmed purchase orders |
| Warehouse receipt loans | Farmers storing grain | Distress selling at harvest | Graded, stored stock |
| Parametric crop insurance | Farmers facing weather risk | No protection at all | Satellite and weather data |
Repayment is deducted when the buyer pays for the crop, which keeps collection costs low. Indonesian platforms such as AwanTunai have shown that transaction data from distribution chains can support lending with low default rates in segments banks considered too risky.
Agri supply chain finance in Bangladesh
Bangladesh is one of the clearest cases. Agriculture still employs a large share of the workforce, the agri-export chain is worth an estimated $8-12 billion, and mobile money reaches most rural households. Yet very few products embed credit or insurance into the chain itself.
Today
40-120% APR
Seasonal input credit from moneylenders and dealers, priced for the lender’s ignorance.
With chain data
Far lower cost
Lenders price risk on delivery history and collect at the point of sale.
The key insight
In agriculture, the supply chain is the credit bureau. The company that sits at the point of purchase can see what no bank can.
Risks to underwrite, not ignore
| Risk | Response |
|---|---|
| Weather and climate shocks | Bundle loans with parametric insurance; diversify by crop and region |
| Side-selling to other buyers | Fair pricing, fast payment and loyalty incentives |
| Price volatility | Short loan tenors tied to a single season |
| Regulatory limits on lending | Partner with licensed lenders or microfinance institutions |
None of these risks is new. Commodity traders and input dealers have managed them informally for generations, which is why they can lend when banks cannot. Agri supply chain finance formalises that knowledge, prices it more fairly, and makes it scalable with data and mobile money.
Who builds it
The most likely winners are not standalone lenders. They are agritech platforms that already buy from farmers, input distributors with deep rural networks, and processors that want a reliable supply. Each holds the transaction data; each needs a lending partner or licence to turn it into credit.
The largest unfinanced value chain on earth does not need a new credit bureau. It needs lenders who can read the one that already exists.
Frequently asked questions
What is agri supply chain finance?
It is lending to farmers and agribusinesses based on their transactions within a supply chain, such as deliveries and purchase orders, instead of land titles or payslips.
Why do smallholder farmers pay such high interest rates?
Because most have no collateral or documented income, banks will not lend to them. Moneylenders and input dealers fill the gap and price in high risk and high collection costs.
How does parametric crop insurance work?
It pays out automatically when a measurable trigger, such as rainfall below a set level, is recorded by weather stations or satellites. There is no need for a field loss assessment.
Which part of the agri chain gets transformed first: input financing, procurement payments, or post-harvest insurance?
Share your view in the comments. This post is part of a 50-part series on fintech in South and Southeast Asia; see the full series index.
Keep reading
Sources
This article is for information and education only. It is not investment, legal or tax advice, and it is not an offer to sell, or a solicitation of an offer to buy, any security or interest in any fund. Market figures come from the third-party sources listed and may change; please check the original sources.