IRR vs MOIC vs DPI: what each venture fund metric tells you, and what it hides
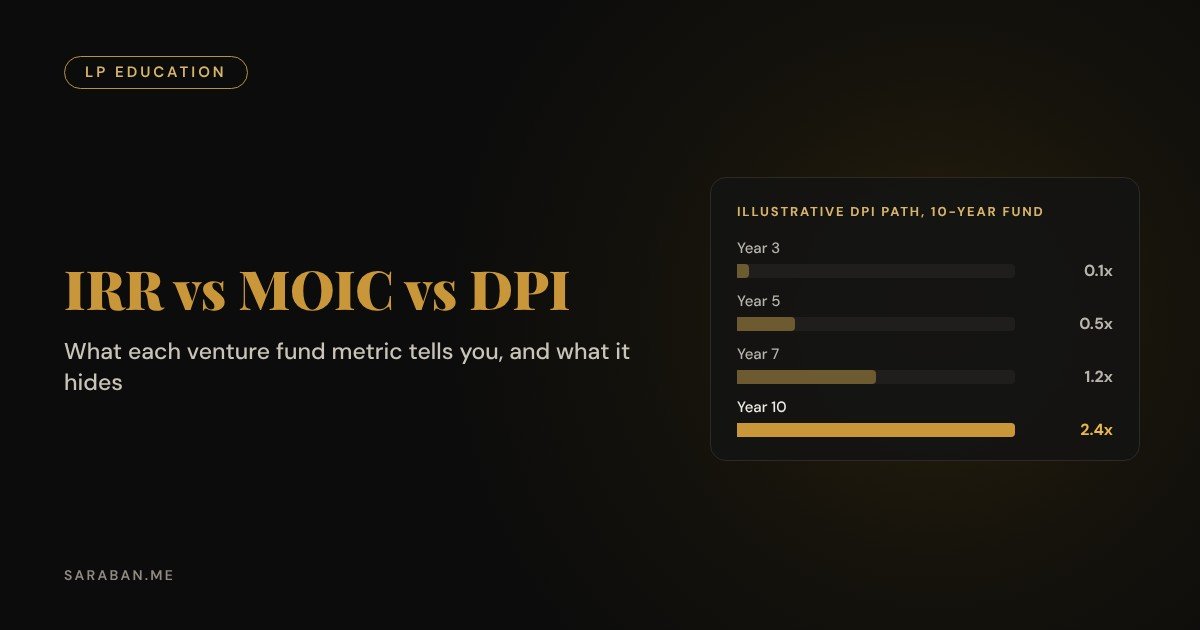
IRR, MOIC and DPI. Fund managers like to quote all three. Each answers a different question, and each can hide something the others reveal.
One metric flatters. One can be timed. One only counts money already in your account.
If you are new to private markets, the irr vs moic vs dpi question comes up in every fund conversation. These three numbers sit at the top of nearly every venture and private equity report, and they are often quoted as if they agree with one another. They frequently do not.
This guide explains each metric in plain language, shows with simple worked examples how they can tell different stories about the same fund, and suggests how to weigh them when you review a manager.
The four metrics in one table
| Metric | Formula | What it tells you | What it hides |
|---|---|---|---|
| MOIC (multiple on invested capital) | Total value ÷ capital invested | How many times the money grew | How long it took |
| IRR (internal rate of return) | Annualised return given the timing of every cash flow | Speed of return | Can be boosted by early, small distributions |
| DPI (distributions to paid-in) | Cash returned ÷ capital called | Realised return | Value still to come |
| TVPI (total value to paid-in) | (Cash returned + remaining value) ÷ capital called | Total return at the fund level | Relies on unrealised marks |
MOIC: the size of the outcome
MOIC is the simplest number. If you invest $100,000 and receive $300,000 back, the MOIC is 3.0x. It ignores time entirely, which is both its strength and its weakness.
Fund A
3.0x in 10 years
Strong multiple, but the annual return is only about 11.6%.
Fund B
2.0x in 3 years
A smaller multiple, but the annual return is about 26%.
Which is better depends on what you could have done with the money in between. That is why MOIC alone is never enough.
IRR: the speed of the outcome
IRR is the annualised rate that makes the present value of all cash flows equal zero. It rewards speed. A fund that returns capital quickly will show a high IRR even if the total multiple is modest.
- Subscription lines can lift IRR. If a fund borrows short-term instead of calling LP capital early, the clock starts later and IRR rises, without the outcome changing.
- Early small wins can flatter IRR. A quick partial exit on a small position can push IRR up even if the rest of the portfolio is slow.
- IRR on unrealised value is an estimate. Before exits, it depends on how holdings are valued.
DPI: the only number already in your account
DPI counts cash actually distributed to LPs. A DPI of 1.0x means investors have their money back. Above 1.0x is realised profit. DPI cannot be inflated by optimistic valuations, which is why experienced LPs weight it so heavily, especially in later years of a fund.
IRR vs MOIC vs DPI: how to read them together
Each metric answers one question. Read together, they tell you whether a track record is real, fast, or still on paper.
| Pattern | What it usually means |
|---|---|
| High IRR, low MOIC, low DPI | Early marks or a quick small exit; the story is still unproven |
| High MOIC, low IRR | Good outcome, but slow; check the opportunity cost |
| High TVPI, low DPI | Value is mostly unrealised; ask how holdings are marked |
| DPI above 1.0x and rising | Capital returned; the track record is becoming real |
A practical rule
Ask for all four numbers, gross and net of fees, by vintage. Weigh DPI most heavily for older funds, and ask how unrealised holdings are valued for younger ones.
The irr vs moic vs dpi comparison also depends on the fund’s age. In years one to four, almost every venture fund shows low DPI and an IRR driven by marks, so comparing young funds on DPI is unfair. From year six onward, DPI should start to dominate the conversation. A manager whose older funds still show mostly unrealised value deserves harder questions than one whose older funds have returned cash.
Net versus gross
Gross figures show what the portfolio earned before fees and carried interest. Net figures show what investors actually received. The gap between them is often several percentage points of IRR. Always compare funds on a net basis.
Questions to ask any manager
- Are these figures gross or net of fees and carried interest?
- Is IRR calculated from the date capital was called or from when it was invested?
- Does the fund use a subscription credit line, and how does that affect IRR?
- How are unrealised holdings valued, and by whom?
- What share of TVPI is already DPI?
MOIC tells you how much. IRR tells you how fast. DPI tells you how much has actually arrived. Only the last one pays the bills.
Frequently asked questions
What is the difference between IRR and MOIC?
MOIC shows how many times invested capital has grown, regardless of time. IRR shows the annualised rate of return, taking the timing of every cash flow into account.
Why is DPI considered the most reliable fund metric?
Because it only counts cash that has actually been distributed to investors. It cannot be raised by optimistic valuations of companies the fund still holds.
What is a good DPI for a venture fund?
It depends on the fund’s age. A DPI of 1.0x means investors have their money back; mature venture funds that perform well typically show DPI well above 1.0x by the end of their life.
Which of these metrics do you weigh most heavily when you review a fund manager, and why?
Share your view in the comments. This post is part of a 50-part series on fintech in South and Southeast Asia; see the full series index.
Keep reading
- The venture capital J-curve, explained for new LPs
- The power law in venture capital: the maths behind every portfolio
- Five questions to ask a fund manager before committing capital
Sources
This article is for information and education only. It is not investment, legal or tax advice, and it is not an offer to sell, or a solicitation of an offer to buy, any security or interest in any fund. Market figures come from the third-party sources listed and may change; please check the original sources.